
magnoliaapplet
magnoliaapplet
Eight Mortgage You Should Never Make
 There is a version of the housing market story that gets told over and over, and it goes like this: prices are high, rates are high, nothing is affordable, and the only people buying are the ones with cash. That version is not wrong, exactly. It is just incomplete.
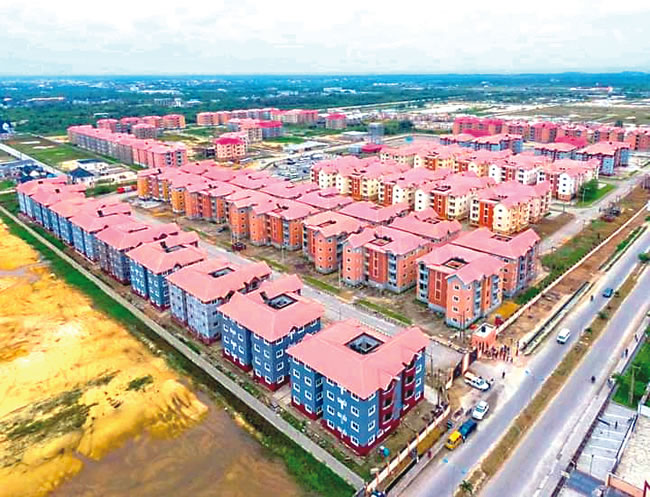 In markets where builders have added meaningful supply in recent years, prices have pulled back. Markets that overheated fastest have cooled most noticeably. But those are the exceptions. Most markets are not working from excess; they are working from scarcity.
 Here is what that creates for someone with solid credit and a real pre-approval in hand: more room to negotiate than the market’s reputation suggests. The panic buyers are gone. The buyers who showed up with letters waiving inspections and offering a hundred thousand over asking have mostly sat back down. What remains is a more functional market, even if it is not a cheap one.
Before you look at a single listing, get your mortgage pre-approval completed and in hand. Not a rough estimate. Not a verbal confirmation from a loan officer you met once. A full pre-approval based on verified income, tax returns, bank statements, and a hard credit pull. Any agent worth working with will tell you the same thing: no pre-approval, no offer.
If the report surfaces findings that change the financial picture of the deal, you have three options, not one, and walking away is a legitimate one of them. You can ask the seller to repair specific items before closing. Signing off on a failing roof or a bad HVAC system is not the same house you made an offer on.
Negotiation works best when it is quiet and well-prepared. Before you make an offer, find out whether the price has been reduced and by how much. A listing with a history of two failed deals in the past month is a fundamentally different negotiation than a property that is drawing multiple showings every day.
The timing question, whether to buy now or wait for a better moment, is the one that trips up more buyers than any other single factor. Waiting for the perfect moment is how people end up renting for another five years when they did not mean to. The more useful question is not whether now is the right time in the abstract; it is whether you can carry the payment without strain.
Buyers who take the time to research properly tend to find that there are still good properties available at realistic prices. Spending twenty minutes with current homes for sale and market analytics is a better use of your time than waiting for conditions that may never arrive.