
iufselma642400
iufselma642400
Ten Tips From A Housing Professional
There is a version of the housing market story that gets told over and over, and it goes like this: prices are high, rates are high, nothing is affordable, and the only people buying are the ones with cash. That version is not wrong, exactly. It is just incomplete.
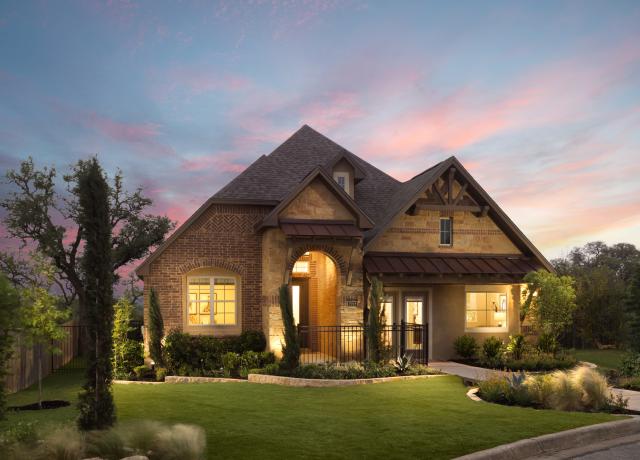 The arithmetic here is brutal and worth understanding clearly. A buyer who financed a $400,000 home at three percent in 2021 pays roughly $1,686 per month on principal and interest. That same loan at a seven percent rate costs $2,661. That gap of nearly a thousand dollars a month is why transaction volume has fallen to levels not seen in decades. Volume collapsed. Prices mostly did not.
 Here is what that creates for someone with solid credit and a real pre-approval in hand: a better chance of getting the house you want without losing a bidding war. The panic buyers are gone. The buyers who showed up with emotion instead of analysis have mostly sat back down. What remains is a more functional market, even if it is not a cheap one.
 Shop at least three lenders before you commit to one. A seemingly small rate difference adds up to around twenty thousand dollars over a thirty-year loan on a four hundred thousand dollar mortgage. Lender fees vary too. Request itemized fee schedules so you can compare apples to apples.
 The appraisal is the lender’s check, not yours. When the appraisal comes in below contract, the deal does not automatically die, but it does require a decision. Ask your agent how common appraisal gaps have been in your target price range and neighborhood.
 The offer price is one variable among several. A longer closing window, a shorter inspection period, a larger earnest money deposit, or willingness to do a rent-back period can all tip a deal in your favor without you spending an extra dollar on the purchase price.
 The timing question, whether to buy now or wait for prices to pull back, is the one that trips up more buyers than any other single factor. Waiting for the perfect moment is how people end up renting for another five years when they did not mean to. The more useful question is not whether now is the right time in the abstract; it is whether you are buying because the numbers make sense for you, not because you feel social pressure to own.
The buyers who come out ahead in this market are not the ones who waited for perfect conditions. They are the ones who treated the purchase like a business decision rather than an emotional one. The most useful thing you can do today is look at homes for sale near you and see whether the numbers work for your situation.